Capture
Records order books and trades from eight exchanges around the clock, for 8,000+ instruments.
Quantitative Research · Trading Systems
Glenrch is a self-funded company with two founders. We wrote our own market-data capture, simulator, strategy and execution code. Before a release ships, it replays recorded market days and must produce bit-identical orders, unless the change is meant to alter trading.
A trading platform we build for our own use. It records exchange market data, and a simulator replays those recordings to test strategies before any of them trade.
We will place buy and sell orders on exchanges that other traders can trade against, then hedge or close the positions that result. We will do this with our own capital only, and our revenue will be the trading profit after fees.
Exchanges need resting buy and sell orders for others to trade against. Placing them is risky: a strategy that looks good on clean data can fail in real markets because of delays, fees and the way orders actually fill. Our simulator tests strategies on recorded markets, with those effects, before they trade.
Once we trade live, traders on those exchanges will have more orders to trade against. The platform itself is for our own use: we do not sell it, take client money or manage money for others.
Records order books and trades from eight exchanges around the clock, for 8,000+ instruments.
Replays recorded days through the production strategy code, order by order, with exchange latency and fees. 40M+ order decisions a day.
Decides, places and hedges orders, with risk checks on every order before it is sent. Today it runs end to end in the simulator; live trading is next.
Parameter optimization across many days and instruments, and model training on the recorded data, moving to GPUs as the models grow. Every result is tested in the simulator before use.
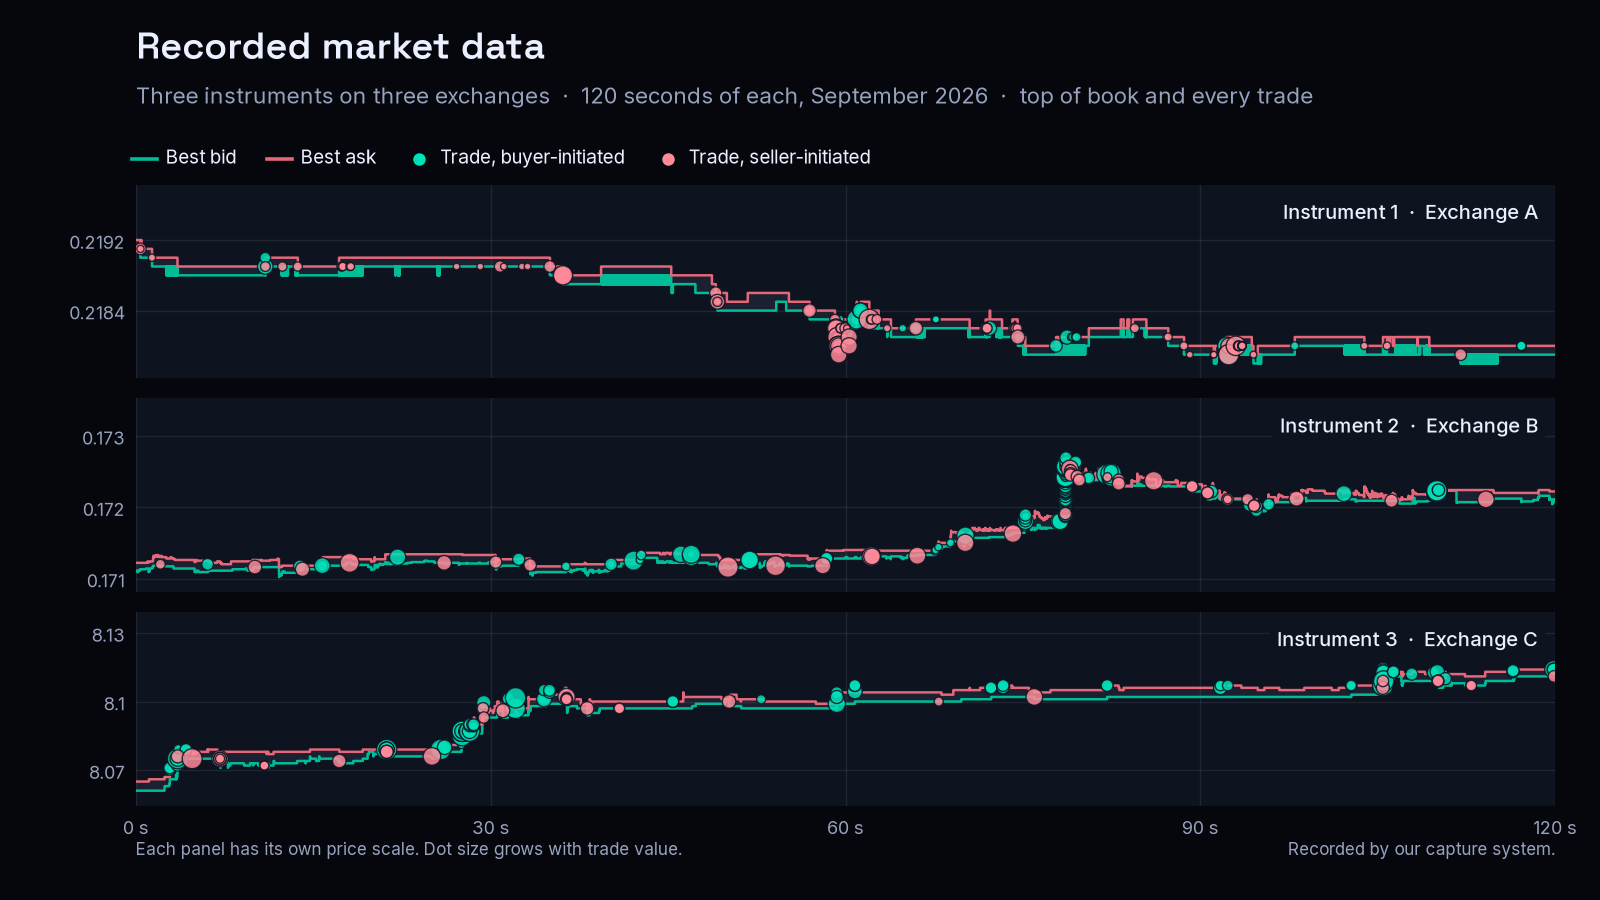
The platform is internal, so there is no public app or sign-up; the diagram and chart above show it working. The two founders built all of it in-house.
Glenrch is self-funded. We build and run systems for systematic, market-neutral trading in digital-asset markets, and we will trade only our own capital. We take no outside money, hold no client assets and keep custody for no one. Every exchange and counterparty account goes through full KYC/AML onboarding.
We wrote everything on the critical path ourselves: market-data capture, simulation, strategy, execution and risk. Capture has recorded live exchanges since January 2026 and has run at production quality since Q2 2026.
Glenrch is the brand of Glen Research LLC, registered in New Jersey, USA.
We will trade only our own money. There are no outside funds, no outside investors and no client assets.
Positions are either hedged or short-term and driven by predictions. Every position has a limit.
Soft and hard limits and the replay check are in place before the first live trade.
Capture, simulation, strategy and execution share one codebase, and everything is tested against the data that capture records.
Order books and trades from eight exchanges, recorded around the clock since January 2026 and at production quality since Q2 2026, for 8,000+ instruments. The capture servers sit close to the exchanges.
Eight exchanges integrated for market data and simulation. We record spot and perpetual markets and use perpetuals for research only. 700+ instruments are modelled, and the engine is built for 10,000.
Replays recorded order books order by order. It reads the same files that capture writes, so strategies are tested on the markets they will trade.
Two builds run the same recorded day. If the orders they produce differ at all, the difference has to be explained before release, so a change in trading behavior shows up before it is deployed.
Every order, fill and decision is recorded. Any moment in production can be replayed from the same data the simulator uses.
Small, fast models make high-frequency decisions, and larger models follow conditions that change more slowly. Language models read news, exchange announcements and on-chain activity, turn them into structured signals, and take part in trading decisions alongside the other models. All of them run inside the limits under Risk & Controls.
Most of our compute goes into research. Each exchange we add brings more data to replay and more models to train. Today this runs on our own servers, and we are moving the parts that grow with the data to the cloud.
Order books and trades from eight exchanges and 8,000+ instruments. These markets never close, so the archive grows every day, and each new day is one more day the simulator can replay.
We replay recorded days through the strategy code. A sweep over instruments, dates and settings splits into independent jobs and comes in bursts: hours of heavy load, then nothing. Rented capacity suits that, so each sweep can be as large as the question needs.
Fast models and slower models are built and tested on the recorded data, and larger models will be trained on GPUs. The work grows with exchanges, instruments, history and the number of settings we test, and we are early on that curve.
Reading text sources (news, exchange announcements, on-chain activity) is a workload of its own, and it grows with each market and source we add.
We use LLM coding agents every day across the codebase. The replay check is what makes that safe: every change is reviewed and must pass replay before it ships, whoever wrote it.
Everything above runs on our own servers today, and none of the numbers on this page are cloud figures. We are moving data storage, simulation sweeps, model training and language-model inference to the cloud. Live trading will stay on small dedicated servers near the exchanges.
Risk checks run in code at four separate layers: the strategy, the order manager, the position manager and the risk manager. A final check runs just before an order goes to an exchange. Every position has a limit.
Every order and every position has caps. An action that would break a limit is rejected before it leaves our system.
Positions are hedged, or short-term and held within strict limits. We take no long-term directional bets.
No strategy or risk change reaches production without a replay on recorded market data. A change that should not affect trading must replay bit-identically; a change that does is reviewed as a diff, on top of normal code review.
Independent risk checks run on every order right before it is sent. Nothing reaches an exchange without passing them.
Two founders. Both previously worked at Tower Research Capital, and both write the code.
Co-Founder
Portfolio manager and engineer; works on applied machine learning and low-latency trading infrastructure. Ex-Tower Research Capital, then 1.5 years building systematic strategies at another trading firm. Earlier: CTO of CUTTR (Princeton, NJ; acquired by Vericept in 2005), where he built the machine-learning spam-detection models, and founder and CEO of Tellicity, a control system for stage machinery used in a concert hall.
in Profile on LinkedInCo-Founder
Ex-Tower Research Capital. Quantitative trader and engineer; works on strategy research and trading systems.
in Profile on LinkedIn